
Social Security COLA 2027 Forecast
Latest update: As of September 15, 2026, the Senior Citizens League (TSCL) estimates a 3.5% Social Security COLA for 2027. The estimate is not official. The final adjustment will depend on September inflation data and the Social Security Administration’s calculation.
Social Security COLA 2027 Forecast. The 2027 Social Security cost-of-living adjustment is attracting significant attention because inflation remains an important concern for retirees, people with disabilities and other Social Security recipients.
The current projection would be higher than the 2.8% COLA for 2026 and the 2.5% adjustment for 2025. However, beneficiaries should not treat the 3.5% figure as a guaranteed benefit increase yet.
What Is the Latest Social Security COLA Forecast for 2027?
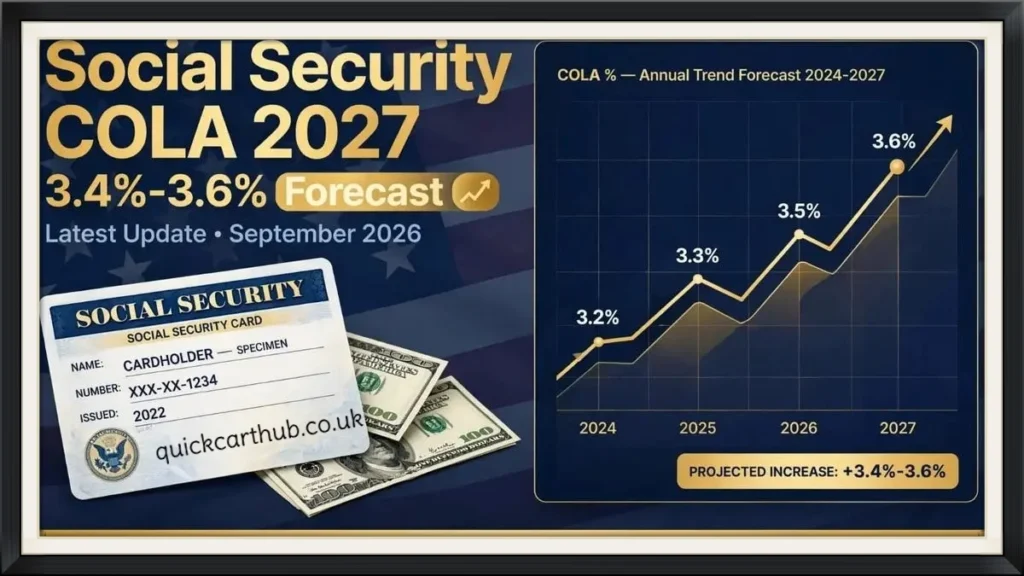
The latest TSCL forecast puts the 2027 COLA at 3.5%.
TSCL released its latest estimate on September 11, 2026, after the August CPI data became available. Its projection was slightly lower than its previous estimate but remained above the 2.8% adjustment received in 2026.
Other forecasts have been in a similar range. Recent reporting has cited estimates around 3.4% to 3.6%, showing that analysts broadly expect the 2027 adjustment to be higher than the previous year’s COLA.
The important point is that 3.5% is still a projection, not the official 2027 COLA.
Current 2027 COLA projection at a glance
| Item | Current information |
|---|---|
| Current 2027 TSCL projection | 3.5% |
| 2026 COLA | 2.8% |
| 2025 COLA | 2.5% |
| August 2026 CPI-W annual increase | 3.5% |
| September 2026 CPI release | October 14, 2026 |
| Expected official COLA announcement | October 2026 |
| Expected effective period | January 2027 |
The Bureau of Labor Statistics reported that the CPI-W increased 3.5% over the year in August 2026. That figure is important because CPI-W data are used in the Social Security COLA calculation.
How Much Could Social Security Benefits Increase in 2027?
If the final COLA is 3.5%, you can estimate the increase by multiplying your current monthly Social Security benefit by 0.035.
For example:
| Current monthly benefit | 3.5% estimated increase | Estimated new benefit |
|---|---|---|
| $1,000 | $35 | $1,035 |
| $1,500 | $52.50 | $1,552.50 |
| $2,000 | $70 | $2,070 |
| $2,500 | $87.50 | $2,587.50 |
| $3,000 | $105 | $3,105 |
These are simple estimates. Your actual payment could differ because Social Security benefits are calculated individually, and deductions such as Medicare premiums can affect the amount you receive.
TSCL estimates that its 3.5% projection would increase an average beneficiary’s monthly check by about $67.90, based on its stated current average benefit figure.
Why the 2027 COLA Estimate Can Still Change
The biggest reason the forecast can change is that September’s inflation data have not yet been released.
The Social Security COLA is based on the average CPI-W for July, August and September. The September figure is therefore the final piece needed to complete the calculation.
The BLS has scheduled the September 2026 CPI release for October 14, 2026.
That means the current 3.5% projection could move higher or lower depending on September consumer prices.
Factors that can influence inflation include:
- Gasoline prices
- Diesel and other fuel costs
- Energy prices
- Housing expenses
- Food prices
- Medical care costs
- Other household expenses
August provided an important signal. The BLS reported that overall CPI increased 0.4% in August, while gasoline prices rose 3.9% during the month.
How Is the Social Security COLA Calculated?
The Social Security Administration does not simply use the overall inflation rate reported in headlines.
Instead, the COLA is based on the Consumer Price Index for Urban Wage Earners and Clerical Workers, or CPI-W.
For the current system, Social Security compares the average CPI-W for the third quarter of the current year with the average for the third quarter of the previous year. The percentage difference determines the COLA.
In simple terms:
- July CPI-W is measured.
- August CPI-W is measured.
- September CPI-W is measured.
- The three monthly figures are averaged.
- That average is compared with the corresponding third-quarter average from the previous year.
- The resulting percentage becomes the COLA, subject to the applicable rounding rules.
This is why the August CPI and September CPI report receive so much attention every year.
What Does August Inflation Data Tell Us About the 2027 COLA?
August data strengthened the case for a COLA above 3%.
According to the BLS, the CPI-W was up 3.5% from August 2025 to August 2026. Overall CPI-U inflation was 3.4% over the same period.
Energy prices were particularly relevant. Gasoline increased 3.9% in August and accounted for more than one-third of the month’s overall CPI increase.
However, one month’s data cannot determine the final adjustment. September’s CPI-W must be included in the three-month calculation.
When Will the Official 2027 Social Security COLA Be Announced?
The official 2027 COLA is expected in October 2026.
The BLS is scheduled to release September CPI data on October 14, 2026. TSCL also identifies October 14 as the date when the Social Security Administration is expected to announce the official 2027 COLA.
Until that announcement, any percentage you see online should be described as a forecast, estimate or projection, rather than the official COLA.
The Social Security Administration’s COLA page currently says the next COLA will be announced in October 2026.
When Would the 2027 Benefit Increase Start?
Once finalized, the 2027 COLA will apply to Social Security benefits payable in January 2027.
The annual adjustment is designed to help Social Security benefits keep pace with changes in consumer prices. COLAs have been automatic since 1975 and are tied to changes in the CPI-W.
The timing of an individual’s actual payment can depend on the normal Social Security payment schedule.
How Does the 2027 Projection Compare With Recent COLAs?
The projected 2027 increase would be higher than the two most recent adjustments.
| Year | COLA |
|---|---|
| 2022 | 5.9% |
| 2023 | 8.7% |
| 2024 | 3.2% |
| 2025 | 2.5% |
| 2026 | 2.8% |
| 2027 | 3.5% projected |
The 2022 and 2023 increases were unusually large because of the inflation surge following the pandemic period. The 8.7% COLA in 2023 remains one of the largest adjustments in recent decades.
A 3.5% adjustment would therefore represent a meaningful increase from 2025 and 2026, but it would still be well below the unusually high 2023 adjustment.
Will the 2027 COLA Keep Up With Inflation?
Not necessarily.
The COLA is intended to reflect inflation, but individual households do not experience inflation in exactly the same way.
A retiree who spends a large portion of their budget on healthcare, housing, utilities or transportation may experience different cost pressures than the broader CPI-W measure.
This is particularly important for senior citizens because a higher Social Security payment does not automatically mean greater purchasing power.
For example, a 3.5% benefit increase can be largely absorbed if essential household costs rise at a similar pace.
Medicare costs can also affect how much of a COLA beneficiaries actually feel in their monthly budgets. Therefore, retirees should look at both their gross Social Security benefit and their expected expenses. Source: News4JAX
What Is the Average Social Security Benefit in 2027?
There is no official average Social Security benefit for 2027 yet because the final COLA has not been announced.
For 2026, the SSA estimated average monthly Social Security retirement benefits at $2,071 after the 2.8% COLA, compared with $2,015 before the adjustment.
If a future 3.5% COLA were applied to $2,071, the simple mathematical estimate would be approximately $2,144 per month.
That is only an illustration, not an official 2027 average. Individual benefit amounts vary based on earnings history, claiming age and other factors.
What Could the 2027 COLA Mean for Retirees?
For many Social Security recipients, the increase could provide additional room in household budgets.
The projected increase may help offset expenses such as:
- Groceries
- Gasoline
- Utilities
- Housing
- Prescription drugs
- Medical services
- Transportation
But beneficiaries should avoid viewing the COLA as a guaranteed improvement in their financial position.
The more useful question is not simply “How big is the COLA?” but “How much will my purchasing power change after my major expenses are paid?”
That distinction matters when planning retirement benefits and monthly household spending.
Is There Really a Social Security Bonus for Retirees?
There is no separate nationwide “Social Security bonus” automatically being paid to retirees simply because of the 2027 COLA.
What people sometimes call a bonus is actually the regular annual cost-of-living adjustment.
If the final COLA is 3.5%, eligible benefits would rise by that percentage under the normal COLA rules. It would not be an additional one-time bonus payment.
Be cautious with social media posts claiming that every retiree will receive a special bonus check.
What Should Social Security Recipients Do Before the Official Announcement?
You do not need to make major financial decisions based solely on an estimate.
Instead:
- Use the current forecast as a planning range, not a guaranteed payment.
- Check the September CPI report when it is released.
- Wait for the official SSA announcement before updating your long-term budget.
- Calculate your personal benefit increase using your actual monthly payment.
- Consider Medicare and other deductions when estimating your net payment.
- Review household expenses, especially healthcare, housing, utilities and transportation.
This approach can provide a more realistic picture than relying on a headline about the projected COLA alone.
Custom FAQs
What is the projected COLA for 2027?
As of September 15, 2026, the Senior Citizens League projects a 3.5% Social Security COLA for 2027. The estimate is not final because September CPI-W data are still needed to complete the official calculation.
Is there a Social Security 2027 COLA increase chart?
Yes. A simple 3.5% projection would look like this:
| Current benefit | Estimated increase | Estimated 2027 benefit |
|---|---|---|
| $1,000 | $35 | $1,035 |
| $1,500 | $52.50 | $1,552.50 |
| $2,000 | $70 | $2,070 |
| $2,500 | $87.50 | $2,587.50 |
| $3,000 | $105 | $3,105 |
These figures are estimates and will change if the official COLA differs from 3.5%.
What is the Social Security COLA 2027 estimate for disability benefits?
Social Security Disability Insurance benefits are generally subject to the same annual COLA as other Social Security benefits. If the final 2027 COLA is 3.5%, an eligible disability benefit of $1,500, for example, would increase by about $52.50 before considering other changes or deductions.
When will the Social Security COLA 2027 estimate be updated?
The estimate can change after additional inflation data are released. The most important remaining data point is September 2026 CPI-W. The BLS has scheduled that report for October 14, 2026, which is also the expected date for the official COLA announcement.
What was the Social Security COLA for 2026?
The official 2026 Social Security COLA was 2.8%. The increase began with Social Security benefits payable in January 2026.
Is there a Social Security COLA 2027 estimate calculator?
You can make a simple estimate by multiplying your current monthly benefit by the projected COLA. For a 3.5% projection, use:
Current monthly benefit × 1.035 = estimated monthly benefit
For example, $2,000 × 1.035 = $2,070.
This is a planning calculation, not an official SSA benefit quote.
What will the official 2027 COLA be?
The official number is not available yet. The final COLA will depend on the July, August and September CPI-W figures. The September CPI release is scheduled for October 14, 2026.
How does inflation affect Social Security benefits?
Inflation is the key reason COLAs exist. The annual adjustment is intended to increase benefits when consumer prices rise. However, because the calculation uses CPI-W, the resulting adjustment may not perfectly match the expenses of every Social Security recipient.
Read more…….